Web portal, Android and iOS

Loan Management Software in South Africa for NCR-Regulated Lenders

Built for South African registered credit providers, micro-lenders and stokvel-backed schemes: rand books, debit order and EFT repayments posted against the loan, and an affordability assessment written around the National Credit Act.

Get started with a 30 day free trial!

Includes full access to AI security features

google playstore iconapple appstore icon
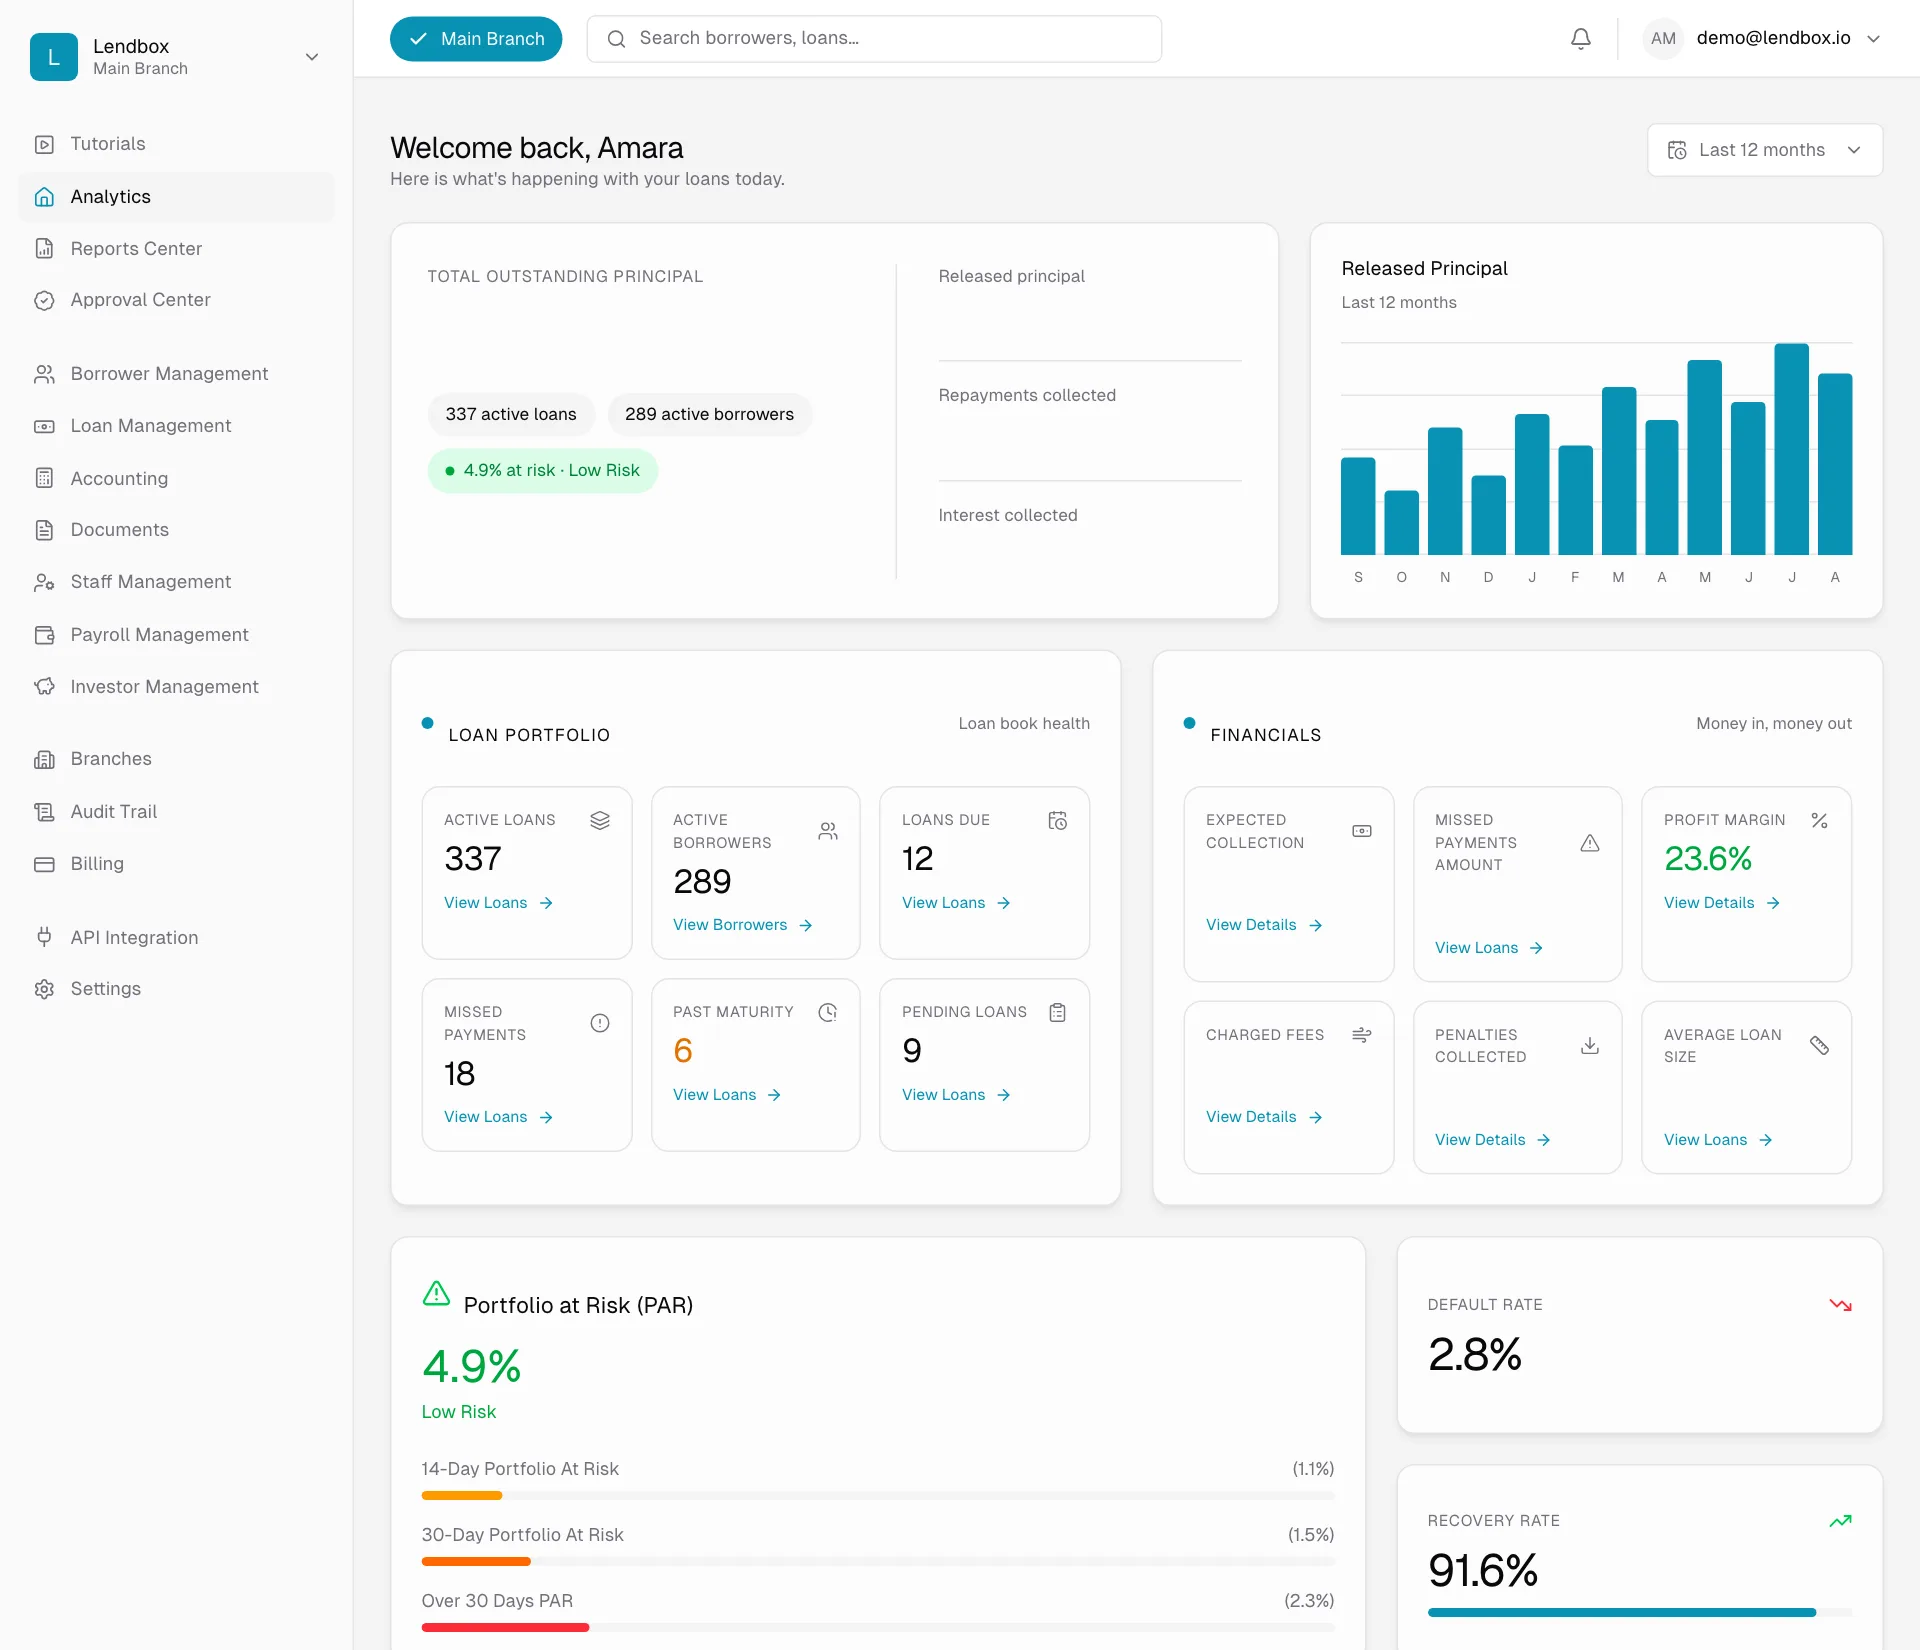
Lendbox dashboard showing a loan book in ZAR

Built for Lenders in South Africa

Loan management software for NCR-regulated lenders in South Africa

Lendbox is loan management software in South Africa for NCR-registered credit providers and micro-lenders: one rand loan ledger with accounting under it, so the affordability record the National Credit Act requires, the schedule the consumer signs and the figures in a return all come from the same loan. See how Lendbox compares with other loan management platforms.

How a South African micro-lender runs its book on Lendbox

From affordability assessment to a rand schedule to the NCR return

The National Credit Act puts the affordability assessment at the front of every loan. These are the stages a registered credit provider already runs; Lendbox keeps the assessment, the agreement and the repayments on one record.

  1. Consumer onboarding

    Add the consumer with the ID number, employer and bank details on file, and let AI document verification check the uploaded ID, payslip and bank statement before the assessment.

  2. NCA affordability assessment

    Run the affordability assessment from the payslip and bank statement, with the discretionary income calculation kept against the loan so it can be shown later.

  3. Pre-agreement and approval

    Print the quotation and agreement with the cost of credit itemised the way the Act requires, and route the loan through the approval ladder with every decision logged.

  4. Debit order and EFT repayments

    Post the month's debit order run as one bulk batch from the Excel template, and record EFT repayments against the loan as they land. Reminders go out by SMS, email or WhatsApp.

  5. Arrears, PAR and the return

    Ageing buckets and portfolio at risk by product, branch and officer give the days-past-due figures a statutory return is built on, drawn from the loans rather than tallied at quarter-end.

Lending in South Africa

Registered with the NCR, assessed under the NCA, judged on the record you kept

South Africa regulates consumer credit through one Act and one regulator. The affordability assessment, the pre-agreement quotation and the cost-of-credit caps are the heart of it, so the software has to keep the record each of them produces. If your South African book is mostly personal loans — unsecured, assessed from a payslip and repaid by debit order — our buyer's guide sets out what to look for in an online loan management system.

Regulator

National Credit Regulator (National Credit Act, 2005)

A lender above the registration threshold registers as a credit provider and submits statutory returns. Lendbox supplies the loan ledger side: ageing buckets per loan, portfolio at risk by product and branch, and a double-entry general ledger with trial balance, P&L and balance sheet.

Affordability

Section 81 affordability assessment

Every credit agreement must follow an affordability assessment of the consumer's income, expenses and existing obligations. Lendbox keeps the assessment on the loan, including the payslip it was read from, and the free affordability calculator on this site is written around the same rules.

Cost of credit

Interest, initiation and service fee caps

The Act caps interest and fees by credit type. Lendbox prints the pre-agreement quotation and schedule with interest, initiation fee, service fee and credit life itemised, so the consumer sees the total cost before signing.

Credit bureaus

TransUnion, Experian, Compuscan, XDS

Registered credit providers submit consumer credit data to the bureaus. Lendbox keeps the full repayment and arrears history per consumer, so the record you submit from is the one your officers see.

Stokvels

Informal savings groups, NASASA-affiliated

Stokvels that lend to members from the pool need a record per member. Lendbox's group loans track each member's share of one loan and split a group repayment per member, and the rand books stay separate from the group's savings.

Sources · National Credit Regulator · National Credit Act, 2005 (Act 34 of 2005) · NASASA — National Stokvel Association of South Africa · Reviewed .

Money in South Africa

Rand in the book, debit orders in a batch, payroll on the same system

The book, statements and reports run in rand. Repayments reach you by debit order or EFT, and Lendbox records them against the loan; it does not sit in the collections flow.

Books in ZAR

Set the workspace currency to rand once and every loan, schedule, statement and financial statement follows.

  • Quotations, agreements and schedules printed in rand
  • Trial balance, P&L and balance sheet in ZAR
  • Consumer statements with a running rand balance

Debit order and EFT repayments

Post the month's debit order run as one bulk batch, and record EFT repayments against the loan when they land.

  • Bulk batches from the Excel template, previewed before they post
  • Unpaid debit orders left open on the loan for follow-up
  • SMS, email and WhatsApp reminders before each due date

South African payroll built in

Staff loans and payroll run in the same workspace, with the South Africa statutory preset applied to each pay run.

  • PAYE and UIF on every run
  • Staff loan repayments deducted on the pay run
  • Payslips emailed to staff from the run

Pricing

Plans for lenders in South Africa

Plans are billed in US dollars by card; the rand amounts below are an indicative conversion, and the rand your bank debits will include its own rate and any foreign-transaction fee. See the full loan management software pricing in South Africa.

Prices shown in South African Rand (ZAR)

Basic

ZAR 420

/month

Billed yearly at ZAR 5,000

1 Branch
1 Staff Member
Business website
24/7 Support
All other features are included
Start 30 day free trial

Business

ZAR 1,500

/month

Billed yearly at ZAR 18,000

2 Branches
3 Staff Members
Custom Domain Name for Business Website
API Integration
Priority Support
All other features are included
Start 30 day free trial

Growth

ZAR 2,300

/month

Billed yearly at ZAR 27,000

3 Branches
6 Staff Members
Custom Domain Name for Business Website
API Integration
Priority Support
All other features are included
Start 30 day free trial

Enterprise

ZAR 3,150

/month

Billed yearly at ZAR 37,000

All features in Growth plan are included
Start 30 day free trial

Questions lenders in South Africa ask

Does Lendbox keep the affordability assessment the National Credit Act requires?

Yes. The affordability tab on each loan records the consumer's income, deductions and existing obligations, reads the payslip (including by AI import), and compares the proposed instalment with discretionary income. The assessment stays on the loan with the documents it was read from, so it can be shown later.

Can it print a pre-agreement quotation with the cost of credit itemised?

The loan agreement and repayment schedule print with interest, initiation fee, service fee and any credit life itemised, so the consumer sees the total cost of credit before signing. The wording of the agreement is yours to set in the document editor.

How do debit order and EFT repayments reach the loan?

The month's debit order run is posted as one bulk batch from an Excel template, one row per consumer, with a preview that flags any row that will not match. EFT repayments are posted by an officer as they land. Lendbox does not run the debit orders; your bank or bureau does. Either way the payment sits on the loan from the day it is posted, so arrears show without a spreadsheet to reconcile against the bank statement — the hassle a loan tracking system exists to remove.

We run a stokvel that lends to members. Does Lendbox fit?

For the lending side, yes. A group loan records each member's share of the principal, and a repayment from the group is split per member. The stokvel's savings pool stays in the account it lives in; Lendbox does not hold deposits.

Is there a South African payroll preset?

Yes. The payroll module ships a South Africa preset with PAYE and UIF, and staff loan repayments are deducted on the pay run. Lines your HR policy adds, such as medical aid, are configured per employee.

Can I get the arrears figures an NCR statutory return asks for?

Lendbox gives you days past due per loan through the ageing buckets and portfolio at risk by product, branch and officer. You present them in the form the return takes; Lendbox does not file the return.

What does Lendbox cost for a credit provider in South Africa?

Basic, for one branch and one staff login, is where a small credit provider starts; Business and Growth add branches and staff. Each plan is charged in US dollars by card, and the pricing grid on this page shows the rand equivalent at an indicative rate alongside it.

Ready to start managing loans in South Africa?
Start your free trial today.